When it comes to driving in Massachusetts, auto insurance isn’t just a good idea—it’s the law. But how do you navigate the complex maze of options, rates, and requirements? Whether you’re a new driver or a seasoned road warrior, understanding how much auto insurance costs in Massachusetts can save you a lot of money and hassle down the road.
In this guide, we’re diving into the nuts and bolts of auto insurance in the Bay State. From breaking down the types of coverage available to uncovering insider tips on securing the best rates, we’ve got you covered. Get ready to become a savvy shopper in the world of Massachusetts auto insurance!


Introduction to Auto Insurance in Massachusetts
Did you know that driving without auto insurance in Massachusetts could cost you thousands of dollars in fines? It’s true! And that’s not all—getting the right coverage can save you from financial ruin in case of an accident.
Auto insurance is essentially a contract between you and an insurance company. You pay a premium, and in return, they promise to cover certain costs if things go south. But here’s the deal: not all insurance is created equal. In Massachusetts, you need to know the options available to make the best choice for your needs.
Types of Auto Insurance Available in Massachusetts
When it comes to auto insurance, Massachusetts offers several options. You have the standard liability coverage, which is mandatory. This covers damages or injuries you cause to others. Then there’s comprehensive coverage, which takes care of non-collision-related incidents—think theft or natural disasters.
Don’t forget about collision insurance. This type covers damage to your own car after an accident. And if you want peace of mind, opt for uninsured motorist coverage. It protects you if you’re hit by someone without insurance.
The Importance of Having Auto Insurance in Massachusetts
Why is having auto insurance so critical in Massachusetts? First off, it’s the law. Driving without it isn’t just risky—it’s illegal. But beyond legality, think about the financial implications. A single accident could leave you battling debts for years.
Pro Tip: Always opt for more than the minimum required coverage. It might cost a bit more upfront, but it could save you significantly in the long run.
Having the right insurance helps you avoid massive out-of-pocket expenses. Plus, it keeps you on the right side of the law. So, make sure you’re covered adequately!
Factors Affecting Auto Insurance Rates
Did you know that your auto insurance rates can vary drastically depending on several key factors? Understanding these elements can save you hundreds, if not thousands, of dollars annually.
Insurance companies in Massachusetts consider a range of factors when determining how much you pay. Let’s break these down so you can make sure you’re not overpaying.
Your Driving History Matters More Than You Think
If you’ve had a few bumps or scrapes, brace yourself. Your driving record is one of the most significant factors insurance companies use to set your rates. A clean record can save you big time, but even a single ticket can increase your premium.
Here’s the deal: insurance companies view past infractions as a predictor of future risk. So, keeping your record clean is crucial.
The Role of Your Vehicle Type
Choosing the right car isn’t just about style or fuel efficiency. The type of vehicle you drive has a direct impact on your insurance costs. Luxury cars or sports vehicles come with heftier price tags due to repair costs and theft risk.
But, if you’re driving a safe, reliable model, you might see lower rates. Insurance companies love cars that are cheap to repair and less likely to be stolen.
Pro Tip: Insurers sometimes offer discounts for vehicles equipped with certain safety features. Make sure you mention if your car has anti-theft systems or advanced safety technology.
Comparing Factors Affecting Premiums
Each factor carries its own weight when it comes to insurance rates. Let’s compare some of these factors:
| Factor | Impact on Premium |
|---|---|
| Driving Record | High |
| Vehicle Type | Moderate |
| Age and Experience | Moderate to High |
| Location | Moderate |
| Credit Score | Low to Moderate |
By knowing how these factors affect your premiums, you can take action to potentially lower your costs. For instance, improving your credit score or moving to a safer neighborhood might help reduce your rates.
Average Cost of Auto Insurance in Massachusetts

Ever wondered how much the average driver in Massachusetts forks out for auto insurance? It’s probably more than you think. The Bay State isn’t the cheapest when it comes to premiums.
On average, drivers in Massachusetts pay around $1,000 annually for their auto insurance. This places Massachusetts in the middle range compared to other states. But, what’s interesting is how much this can fluctuate based on factors like your location within the state and the coverage you choose.
Cost Differences Based on Coverage Levels
Insurance isn’t a one-size-fits-all game. While basic liability might seem like a steal, opting for comprehensive coverage gives you that extra peace of mind but at a price. In Massachusetts, you could see a difference of up to $500 annually between liability-only and full coverage policies. So, you need to decide what level of protection is worth the premium.
Imagine this: you’re saving a few dollars upfront by choosing just the basic coverage, but a fender bender could leave you digging deep into your pockets. Choosing the right coverage is crucial.
Pro Tip: Always weigh the cost of higher coverage against the potential out-of-pocket expenses you might face after an accident.
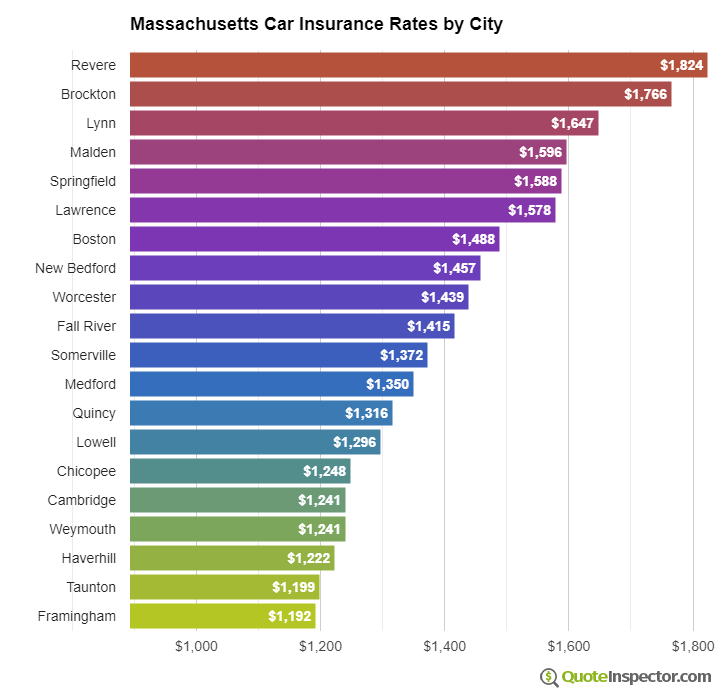
Average Costs by City or County
Location, location, location. The city or county you live in can dramatically alter your insurance rates. Let’s break it down:
| City/County | Average Annual Cost |
|---|---|
| Boston | $1,200 |
| Worcester | $1,050 |
| Springfield | $1,030 |
| Lowell | $980 |
| Cambridge | $1,150 |
Notice a pattern? Urban areas like Boston and Cambridge often have higher rates due to traffic congestion and higher accident rates. Meanwhile, some smaller cities enjoy slightly lower premiums. The closer you are to bustling city centers, the more you might end up paying.
How to Find the Best Auto Insurance Rates
Ever wonder if you’re overpaying for auto insurance in Massachusetts? You’re not alone. Many motorists feel the pinch, but the good news is you can find better rates!
Here’s the deal: auto insurance rates vary significantly between providers, and a few smart strategies can help you slash your premiums. It’s all about comparison and negotiation.
Methods to Compare Auto Insurance Quotes
Start by shopping around. You might be surprised by how much you can save just by spending a little time comparing rates. Use online tools to get quotes from different providers. This process can be quick and painless, and it reveals who offers the most competitive rates.
Consider using an insurance broker. They’re like matchmakers for you and the best policy. Plus, they can often secure special discounts that you might not find on your own.
Effective Ways to Lower Auto Insurance Rates
Here are two golden methods to cut your insurance costs:
- Bundle Your Policies: Insurers love when you bring them more business. Combine your auto insurance with other policies like home or renters insurance to unlock discounts.
- Improve Your Credit Score: Did you know that a better credit score can lead to lower premiums? It’s true! Pay your bills on time and reduce debt to boost your score and possibly reduce your rates.
Tips for Negotiating Better Insurance Premiums
Negotiation isn’t just for buying cars; it works for insurance too!
- Always ask for discounts. Many insurers offer them for safe driving, good grades, or being a loyal customer.
- Raise your deductible. A higher deductible means lower premiums. Just ensure you can pay it if needed.
- Review your coverage annually. Circumstances change, and so should your policy.
- Leverage competitive quotes. Use lower quotes from other insurers as bargaining chips with your current provider.
Pro Tip: Regularly checking your insurance rates can lead to significant savings over time—don’t get too comfortable!
Legal Requirements for Auto Insurance in Massachusetts
Think you can skip out on auto insurance in Massachusetts? Think again. The state has some of the strictest insurance laws in the country. It’s not just about protecting yourself; it’s the law.
Here is the deal: if you’re driving in Massachusetts, you need to have a minimum level of coverage. This isn’t optional. But what exactly do you need?
Minimum Coverage Requirements
In Massachusetts, drivers must carry four types of coverage. Failing to have any of these can lead to hefty penalties, including fines and license suspension. Here’s a breakdown:
| Coverage Type | Minimum Amount |
|---|---|
| Bodily Injury to Others | $20,000 per person / $40,000 per accident |
| Personal Injury Protection (PIP) | $8,000 per person |
| Bodily Injury Caused by an Uninsured Auto | $20,000 per person / $40,000 per accident |
| Damage to Someone Else’s Property | $5,000 per accident |
Penalties for Non-Compliance
Don’t have the required coverage? Massachusetts doesn’t mess around. If you’re caught driving uninsured, you’re looking at fines ranging from $500 to $5,000. And that’s just the start.
You might also face a suspension of your vehicle registration and driver’s license. What’s worse? Getting caught driving with a suspended license can lead to even more severe consequences.
Pro Tip: Always keep a copy of your insurance policy in your glove compartment. It could save you a lot of trouble if you get pulled over.
Common Auto Insurance Discounts in Massachusetts
Did you know that you could save up to 30% on your auto insurance premiums just by stacking discounts? In Massachusetts, there are several ways you can reduce your insurance costs, but most drivers miss out because they don’t know about them.
Insurance companies offer a variety of discounts to make coverage more affordable. BUT, not all discounts are available to everyone. You have to know what they are and how to qualify. Let’s break down the most common discounts you can snag in Massachusetts.
Multi-Policy Discounts
Want a quick way to save? Bundle your auto and home insurance with the same provider. Most insurers offer a 10-20% discount if you do. Here’s the deal: it’s not just about convenience—it’s about slashing those premiums.
Good Driver Discounts
Are you a safe driver? Then you deserve a break on your premiums. If you haven’t had an accident or moving violation in the last three to five years, you could qualify for a good driver discount of up to 25%. Insurance companies love low-risk drivers, and they’re willing to reward you for it.
Low Mileage Discounts
Do you drive less than 7,500 miles a year? If so, you might qualify for a low mileage discount. Some insurers in Massachusetts offer this discount because less time on the road generally means less risk for accidents. It’s an easy way to put some money back in your pocket.
Student and Young Driver Discounts
Have a student in the family? You’re in luck. Students who maintain a “B” average or higher often qualify for a good student discount. Plus, if you have a young driver, completing a driver’s education course can also earn you a discount.
Impact of Discounts on Overall Insurance Costs
So, what’s the bottom line? These discounts can significantly lower your insurance bill. By stacking multiple offers, you could see your premiums drop by 30% or more. Pro Tip: Always ask your insurer about potential discounts. Even small savings add up over time!
Final Thoughts
By now, you should have a solid understanding of how much auto insurance costs in Massachusetts and what factors influence these costs. Remember, the key to saving money is to shop around, leverage discounts, and maintain a clean driving record. Armed with this knowledge, you’re ready to hit the road with confidence, knowing you’ve got the best coverage at the best price.
FAQ Section
How much does auto insurance typically cost in Massachusetts?
The average cost of auto insurance in Massachusetts varies depending on several factors, but you can expect to pay around $1,200 to $1,500 annually on average.
What factors affect auto insurance rates in Massachusetts?
Factors such as age, driving history, type of vehicle, credit score, and location can all influence your auto insurance rates in Massachusetts.
What is the minimum auto insurance coverage required in Massachusetts?
Massachusetts law requires drivers to have a minimum coverage of $20,000 per person and $40,000 per accident for bodily injury liability, among other requirements.
Can I get discounts on auto insurance in Massachusetts?
Yes, many insurers offer discounts such as good driver discounts, multi-policy discounts, and discounts for taking defensive driving courses.
How can I lower my auto insurance rates in Massachusetts?
Compare quotes from different providers, consider raising your deductible, and maintain a clean driving record to lower your insurance rates.